Information regarding the purchase of homes at the reduced 9% VAT rate
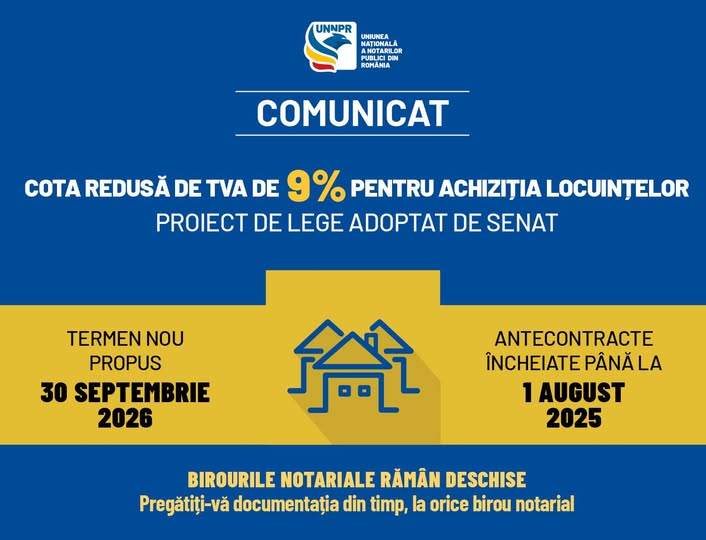
In view of the numerous enquiries addressed to notarial offices regarding the possibility of concluding sale and purchase agreements for homes subject to the reduced VAT rate of 9% following the resumption of ANCPI services, the National Union of Notaries Public of Romania wishes to inform the public of the following:
The Union welcomes the adoption by the Romanian Senate of the draft law aimed at protecting individuals who were unable to complete the purchase of their homes within the established deadlines due to the unavailability of cadastre and land registration services. In the version adopted by the Senate, the draft law provides for a new deadline – 30 September 2026 – by which individuals who, by 1 August 2025, concluded a legal instrument providing for an advance payment towards the purchase of a home may purchase a single home at the reduced VAT rate of 9%. The draft law also provides for the possibility of reimbursement of the VAT difference for those who were required to complete their transaction at the standard VAT rate after the tax relief had expired.
The draft law is due to be debated by the Chamber of Deputies, as the decision-making chamber. If adopted, the law will be submitted for promulgation and subsequently published in the Official Gazette of Romania.
Important information for citizens: notarial offices continue to operate. During this period, interested persons may contact notaries public for consultations, verification of the legal status of properties, including verification of compliance with the legal requirements for purchasing a home at the reduced VAT rate, and preparation of the necessary documentation, so that the relevant instruments can be signed as soon as cadastre and land registration services resume their activity.
At the same time, the National Union of Notaries Public of Romania expresses its confidence that similar measures will also be adopted with regard to potential heirs who were unable to complete succession proceedings during this period and who, as a result, would otherwise be required to pay the 1% tax calculated on the value of the estate.